

Cash Advance – Quick Borrow
by TIMECORE Studio
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 10.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
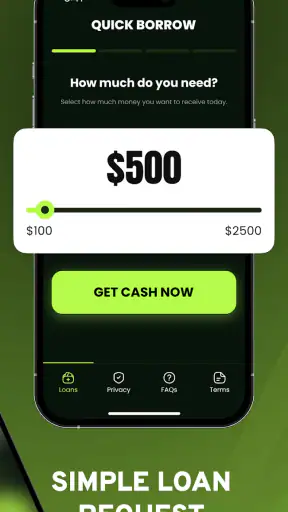
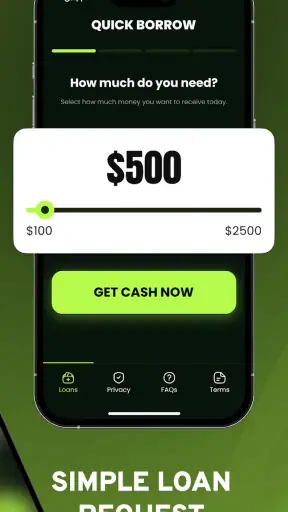
 Analysis by Getfullapps
Cash Advance – Quick Borrow is a finance app from TIMECORE Studio that I approached with a very specific question: is it useful beyond the moment when someone urgently needs money? Its purpose is straightforward—helping users request cash advance and personal loan offers online—but the real test is what happens after the first request. A borrowing tool can feel convenient in a stressful afternoon and still become a poor habit if it encourages rushed decisions.
After spending time with the app, I see its main appeal in its directness. It is free to install, aimed at an Everyone audience, and available for devices running Android 7.0 or later. The current release is version 1.0.7, and its presence in the finance category is reflected by an average rating of 4.7 from over 900 ratings. Those figures suggest that many users find the basic experience approachable, but they should not be mistaken for a guarantee that every offer will suit every borrower.
What the first week feels like
My first impression was that Cash Advance – Quick Borrow is designed for people who want to begin an online request without visiting a branch or working through a traditional banking appointment. That can be valuable when the need is small, time-sensitive, and clearly understood. The app gives the process a more focused shape than searching across unrelated financial websites, which makes it easier to concentrate on the request itself.
The important distinction is that the app is an offer-request tool, not money that should be treated as automatically approved or instantly available. I would open it with a clear amount and repayment plan in mind, rather than hoping the application will solve an undefined shortage. That small change in attitude matters. A fast request can save time, but it can also make borrowing feel less serious than it really is.
For a realistic example, imagine a household facing an unexpected repair shortly before payday. I could use the app to explore whether a cash advance or personal loan offer is available, then compare the repayment obligation with the next few weeks of essential expenses. The useful part is not simply submitting the request. It is having a fixed stopping point: if the repayment would force me to borrow again for groceries, transport, or bills, I would leave the process rather than continue because the app feels convenient.
During a first session, I would keep personal information and financial details close at hand and read every screen carefully before submitting anything. Finance apps reward patience more than speed. I would also verify that the contact details and identity information are accurate, since a mistake in an application can create extra friction later. The app’s simple promise is attractive, but the user still has to supply the judgment.
One of the less obvious strengths is that the app can serve as a decision checkpoint. Instead of accepting the first borrowing idea that appears in a search engine, I can pause inside one finance-focused workflow and ask whether I actually need credit, how quickly I can repay it, and whether another option is safer. Used this way, it is not merely a shortcut to borrowing; it is a prompt to make the request more deliberate.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
That first-week appeal is strongest for someone who already knows why they are applying. It is weaker for a user who is browsing out of curiosity or hoping to discover how much they can borrow. The latter approach can turn an exploratory tool into a source of temptation, particularly when the original financial problem is not urgent.
How it compares with familiar alternatives
The usual alternatives are a bank’s own mobile app, a credit union, an employer-based advance service, or direct contact with a lender. A bank app may be better when I already have an established relationship and want clearer access to existing account information. A credit union may be preferable when personal guidance and a longer-term relationship matter more than a quick online request. An employer-based option can sometimes fit a short gap in pay better than a personal loan, depending on its terms.
Cash Advance – Quick Borrow sits in a different place. Its value is convenience and a focused starting point for exploring offers. Its weakness is that convenience alone does not tell me whether the eventual repayment terms are competitive or comfortable. I would therefore use it as one step in comparison, not as the only financial source I consult.
A practical habit is to write down the total amount I would repay, the timing of each payment, and the consequence of missing one before agreeing to anything. If the information is difficult to understand, that is a reason to slow down, not a reason to assume the offer is harmless. The app can make the request easier; it cannot replace a full comparison of the obligation.
Whether it earns a place month after month
The harder question is recurring value. Most people do not need a cash advance app every day, and I would not recommend opening this one as part of a routine morning finance check. Its long-term usefulness depends on whether it remains a controlled emergency option rather than becoming a regular bridge between paydays.
For occasional use, the app may deserve a place on a device because it keeps a potential request path available when an unexpected expense appears. That does not mean I would keep borrowing through it automatically. I would revisit the reason for each request, record the repayment date in my normal budget, and remove the app if I noticed that I was checking it whenever money felt tight.
This is where the distinction between access and habit becomes important. An emergency tool can be valuable precisely because it is not used often. The long-term benefit comes from knowing where to begin if a genuine need appears, while maintaining other safeguards such as an emergency fund, a bill calendar, and a list of lower-cost alternatives. The app should support those habits, not replace them.
I also think the free price changes the psychology of the decision. There is no installation cost to create a barrier, which is convenient, but that can make it feel too easy to keep available “just in case.” I would treat free access as a technical convenience, not as evidence that borrowing itself will be inexpensive. The financial cost is determined by the offer and repayment conditions, not by the download.
Its audience reach is still relatively modest at over 10 thousand installs, which makes me view it as a focused tool rather than a universally established finance platform. The strong average rating is encouraging, but ratings usually reflect the ease of the app experience more than the complete financial outcome of every loan. I would use that feedback as a sign that people find it usable, not as a substitute for reading the terms of an offer.
One useful monthly workflow would be to keep the app dormant unless a specific expense appears, compare its possible offer with a bank or credit union option, and then delete any saved notes or reminders once the decision is complete. This prevents the application from becoming a standing invitation to borrow. It also makes the user’s own budget the primary system, with the app playing a limited supporting role.
What maintenance really involves
Maintaining a finance app is not only about updating the software. The current version, 1.0.7, matters because staying current can help avoid problems caused by an outdated application. I would install updates through the normal app marketplace, review the app’s access requests when prompted, and avoid entering sensitive information while connected to an untrusted network. These are simple habits, but they are especially important when an app handles financial requests.
I would also keep the phone itself protected with a screen lock and avoid leaving application screens open where another person could see private information. If I stopped using the app, I would remove it rather than letting an unused borrowing tool remain on the device indefinitely. The maintenance burden is not huge, but finance apps deserve more care than casual entertainment downloads because the information involved can be sensitive.
Another maintenance task is personal record-keeping. I would save the details of any request and repayment commitment in a separate budget record, using the app only as the place where the request begins. That gives me a stable reference if I later need to check what I applied for or when a payment is due. Relying on memory, notifications, or a single app is a weak system for something that affects household cash flow.
I would not assume that an app update changes the financial suitability of an offer. Software maintenance can improve the interface or compatibility, but it does not turn an expensive obligation into an affordable one. The user still needs to examine the amount, repayment schedule, and total responsibility each time. This is one reason the app is easier to maintain technically than financially: the difficult work is disciplined decision-making.
Where fatigue begins
The first source of fatigue is repetition. If I repeatedly use a cash advance to cover normal expenses, the app may feel helpful while the underlying gap grows. That is not a flaw that a smoother interface can solve. In that situation, a budget review, a conversation with a bank or credit union, or advice from a qualified financial counselor would be more appropriate than another request.
The second is comparison fatigue. A user in a hurry may focus on receiving an offer and overlook the wider question of whether it is the best available option. I would avoid making a decision during the most stressful part of the emergency. Even a short pause to compare the offer with an existing bank facility, a payment arrangement, or a trusted personal option can reveal a safer path.
There is also emotional fatigue. Repeatedly opening an app associated with financial pressure can make money worries feel constant. If I found myself checking it without a specific need, I would take that as a warning sign and remove it from my everyday routine. The app is not designed to solve the causes of recurring financial stress, and expecting it to do so would lead to disappointment.
Another limitation is that a digital request cannot provide the same personal explanation as speaking with a knowledgeable adviser. Someone unfamiliar with lending language may need help understanding an offer, and an app-based process can encourage users to proceed alone. I would ask a trusted, financially responsible person to review the commitment when the situation is serious, especially if the repayment could affect rent, utilities, food, or other essentials.
Cash Advance – Quick Borrow is also not the right choice for someone seeking long-term debt management, investment guidance, savings automation, or detailed household budgeting. Its role is narrower. A dedicated budgeting app is better for tracking spending, while a bank or credit union may be better for discussing structured borrowing. Choosing the right tool depends on the problem, and not every money problem is a cash-access problem.
Who will benefit and who should skip it
I can recommend trying it to an adult who wants a convenient online starting point for a specific short-term need, understands that an offer must be evaluated carefully, and can calculate repayment without endangering essential expenses. The Everyone content rating makes it broadly accessible from an app-store perspective, but responsible borrowing still requires adult judgment and financial awareness.
I would tell someone to skip it if they are already using one advance to repay another, cannot explain how the repayment fits into their budget, or are applying simply because the app makes borrowing feel available. I would also choose a different route if I needed advice rather than an online request, or if I had an existing financial provider that could offer clearer terms through a relationship I already trust.
A useful rule is to decide the maximum affordable repayment before opening the app. If the available offer exceeds that limit, the answer is not to stretch the budget to match it. The amount I can borrow and the amount I should borrow are completely different questions, and the second one is the only question that protects my future cash flow.
My long-term verdict
Cash Advance – Quick Borrow earns limited, conditional space on my phone. I like its focused purpose, free access, and low-friction starting point for exploring cash advance and personal loan offers. TIMECORE Studio has positioned it as a practical finance utility rather than a broad money-management suite, and that narrow role is its clearest strength.
Still, I would not describe it as an app to use habitually. Its lasting value comes from occasional availability, careful comparison, and a firm repayment plan. The moment it becomes part of a recurring cycle, its convenience stops being an advantage and becomes part of the problem. That trade-off should be visible before the first request, not discovered after several borrowing decisions.
My recommendation is to keep the app in the “emergency option” category, alongside a written budget and at least one alternative source of help. Check the offer carefully, record the full commitment outside the app, and walk away when the numbers do not fit. For someone who needs a quick online place to begin, it may be useful. For someone looking for lasting financial stability, it is only one small tool—and certainly not the foundation of a healthy money routine.
Pros
- Fast application process with minimal paperwork
- Clear repayment terms shown before accepting an advance
- Useful for handling unexpected short-term expenses
- Simple interface that is easy for first-time users
- May offer flexible borrowing amounts based on eligibility
Cons
- Approval and loan availability can vary by state or location
- Late payments may lead to additional fees or collection activity
- Borrowing limits may be too low for larger financial emergencies
- Eligibility may require access to income or banking information
- Frequent advances can make it harder to manage future paychecks
FAQs for Cash Advance – Quick Borrow
What is Cash Advance – Quick Borrow, and how does it work?
Cash Advance – Quick Borrow is a financial app designed to help eligible users request a short-term cash advance through a mobile device. After creating an account, you generally provide personal and financial information, review the available offer, and submit a request. Approval, loan amount, fees, and repayment terms depend on the provider’s eligibility checks and may vary between users.
Is Cash Advance – Quick Borrow a legitimate and safe app to use?
Before using Cash Advance – Quick Borrow, download it only from an official app store and verify the developer, privacy policy, permissions, and customer-support details. Financial apps handle sensitive information, so users should avoid unofficial APK files and carefully review how data is collected and shared. No app can guarantee approval, and users should be cautious of requests for upfront payments.
How much money can I borrow, and how quickly will I receive it?
The amount available through Cash Advance – Quick Borrow is usually determined by factors such as identity verification, income, account history, and the lender’s policies. Some applications may receive a decision quickly, but approval is not guaranteed. Even after approval, delivery times can depend on your bank, payment method, weekends, holidays, and any applicable processing fees.
What fees, interest, and repayment terms should I expect?
Users should read the complete offer before accepting a cash advance, including the annual percentage rate, interest, origination or subscription fees, late charges, repayment date, and any optional services. Short-term borrowing can become expensive if repayment is delayed or renewed. The exact cost should be shown in the app or lender agreement, and terms may differ by location and applicant.
What information and permissions does the app require?
Cash Advance – Quick Borrow may request information needed for account creation, identity verification, income assessment, bank connectivity, and repayment processing. Review every permission carefully and provide only information that is genuinely necessary. Check the app’s privacy policy to understand data retention, sharing, and deletion options. If the requested access seems excessive or unclear, do not continue until you have verified the provider.











